The cohort
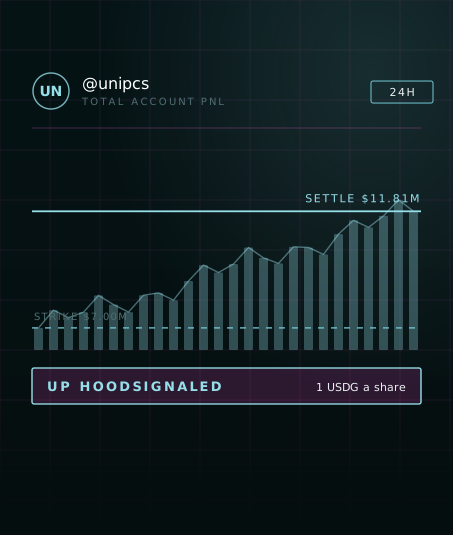
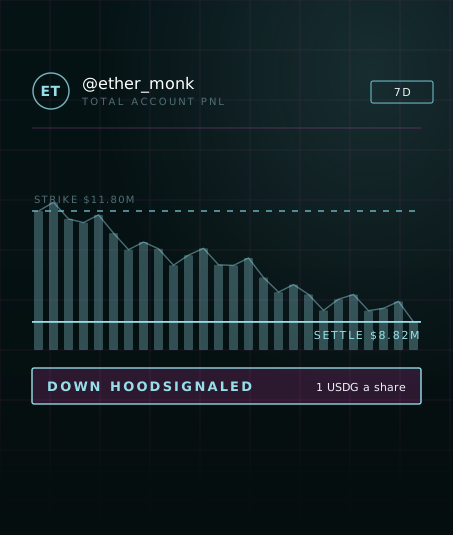
The ten traders at the top of fomo's board were listed at the same moment, each with a one-day and a seven-day market. Listing is permissionless, so none of them were asked, and any of them can end it with one signature.
Every market opened at exactly 50c a side. With no flow yet the protocol has to quote something, and over 24 hours the difference between a good trader and a lucky one is almost entirely noise. Opening flat says what is actually known and lets the first trades do the estimating.
- Seeded with $10.00 of liquidity each.
- Priced by a fixed-product market maker, so there is a live price even on an untouched market.
- A share costs p and redeems for exactly 1 USDG if it wins, which makes the price the probability.
How the day ran
The keeper held a logged-in session for the whole window and never stopped reading. Each reading landed as a file rather than a row in a database, because a settlement that commits the hash of a file nobody can read proves nothing to anyone.
At the close the settlement job took the median of the three snapshots nearest that moment for each market, compared it to the baseline recorded at the open, and posted ten outcomes with ten hashes.
The seven-day markets on the same ten callers stayed open. Further templates are already defined in the protocol: activity markets on whether a caller opens a new position, target-return and range-bound markets shaped by their volatility, streaks, and head to head pairs.
None of those change the machinery below them. They list once the launch pair has volume.
What came next
The first cohort is ten callers with a one-day and a seven-day market each, opening together when the oracle goes live.